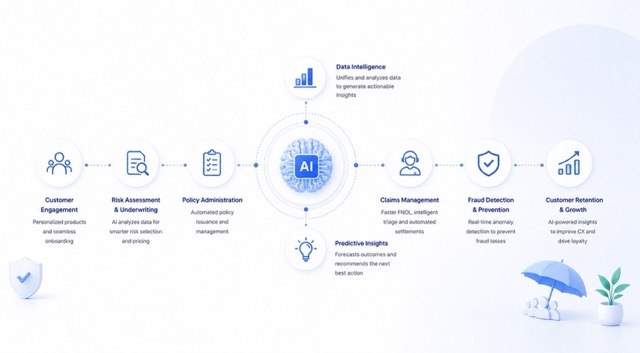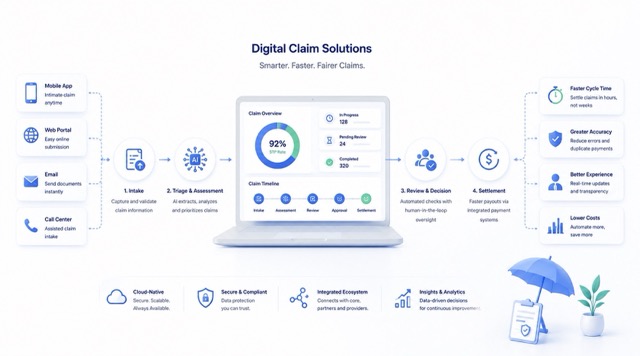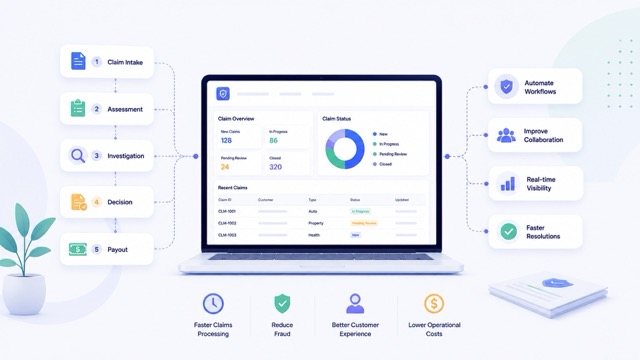


Claims management system software provides the infrastructure for coordinating claim intake, validation, investigation, adjudication, settlement, and closure, while insurance claim management software connects these processes with policy, payment, document, and workflow systems.
As insurers handle larger claim volumes across multiple products and distribution channels, coordinating these activities becomes increasingly difficult. Delays rarely occur because claims are complex, they occur because decisions, information, and responsibilities are spread across multiple teams and systems.
Claims management system software helps insurers organize this operational complexity. Rather than simply digitizing claim records, it provides a structured environment for managing claims from First Notice of Loss (FNOL) through settlement while ensuring every stage follows consistent operational processes.
Why Managing Insurance Claims Has Become More Operationally Complex?
Claims operations have evolved far beyond recording losses and issuing payments. Every claim now passes through multiple operational checkpoints before it can be approved, investigated, or settled.
Different products follow different claims procedures. The motor claim may be dependent on cost estimates and surveyor inspection, whereas claims for commercial properties are usually dependent on the interpretation of the insurance policy. Health, liability, cyber, and marine claims introduce their own documentation, regulatory, and settlement requirements.
The challenge isn't handling individual claims, it's managing thousands of claims that all follow different operational paths.
Every claim also introduces operational decisions. Coverage needs to be confirmed, reserves set aside, claims adjusters assigned, documentation analyzed, signs of fraud identified, vendors coordinated, approvals completed, and customer communications updated. Each one of those decisions impacts the speed at which the claims process happens.
This becomes more difficult when manual coordination is used. Claims processing teams use emails, spreadsheets, disconnected policy management systems, document management systems, and manual follow-up to process claims across departments. The larger the number of claims, the harder it is because of this disconnected process.
Increased complexity due to regulatory requirements. Insurance companies need to ensure audit trail availability, compliance with claims management regulations per jurisdiction, recording of settlement decisions, and claims consistency and fairness.
Modern claims operations therefore require more than claims expertise. They require operational control over how claims move through the organization, how decisions are applied, and how multiple stakeholders remain coordinated throughout the claims lifecycle.
Also Read: Healthcare Fraud Detection Tools & Techniques
What Happens Between First Notice of Loss (FNOL) and Claim Settlement?
A claim doesn't move directly from notification to payment. Insurers will need to carry out various activities between FNOL and claims settlement, all geared towards confirming coverage, assessing losses, investigating liability and ensuring that claims comply with internal policies and regulations.
These activities are typically coordinated through claim processing software or an insurance claim processing system, with integrations to policy administration, document management, payment, fraud, and external service systems.
- Registration and Coverage Validation: When a loss occurs, it needs to be reported and registered. The registration process involves validation of the claim by checking such information as coverage, policy limit, any exclusions, deductibles and policy effective dates. It is important to note down coverage problems at an early stage to avoid unnecessary investigation and delays in processing the claims.
- Investigation and Loss Assessment: For different types of claims, insurers employ adjusters, surveyors, investigators or even outside experts for the purpose of assessing the reported loss. Documents, photographs, repairs estimates, medical records and incident reports among others are checked to assess the loss and determine whether more investigation is necessary.
- Reserve Management and Claims Review: As more information becomes available, insurers establish or revise claim reserves to reflect the expected cost of settlement. At the same time, claims are reviewed for coverage exceptions, liability concerns, potential fraud indicators, and approval requirements before settlement decisions are made.
- Claim Adjudication and Decisioning: Once the required claim information has been validated and the relevant evidence has been collected, the claim can be evaluated against coverage, policy, contractual, and business rules. The adjudication process determines the applicable claim outcome, such as approval, denial, partial payment, or referral for additional review. In automated environments, claims adjudication software evaluates these conditions consistently while routing exceptions to human reviewers when the available data or rules are insufficient for an automated decision.
- Settlement and Closure: After completing all the reviews, the claim proceeds towards settlement. Payments are processed, recovery is considered, if any, and the claim is settled after final documentation has been done. Managing such processes effectively is not simply about following the status of the claim.
How Claims Management System Software Brings Structure to the Claims Lifecycle
A claim management system provides the operational framework by linking activities that are managed in different systems and manual processes. Insurance claim management systems can centralize claim data, workflows, documents, approvals, and integrations while providing a consistent operating model for claims teams.
Depending on the insurance line, the same architecture can support insurance claim software, life insurance claim software, medical insurance claim software, or broader claim administration software requirements.
Below are some of the key operational capabilities that provide the means for creating better consistency and control of the claims lifecycle.
- Centralized Claim Management
Claim management creates information from several sources that include policy management systems, customer communications, adjusters' reports, documentation and payments. A centralized claims environment combines all the information in one place and gives the claims teams visibility into the claim without having to use multiple applications.
- Standardized Claims Workflows
Each claim requires a different process, but each claim needs to go through an operational process. Claims management software helps insurance companies establish their standard assignments, investigations, approvals, documentation and settlements.
- Improved Collaboration within Claims Management Processes
Claims handling is usually associated with various stakeholders such as adjusters, surveyors, repair partners, legal staff, medical personnel, finance team, and customer support staff. A proper claims management system facilitates improved collaboration through the provision of a shared basis of data and processes that everyone must work with.
- Operational Visibility
In order for claims managers to gain an insight into their workload, aging claims, investigation queue, time of settlement, movement in reserve, and approval queue, operational visibility becomes key. The need to gather data from other systems becomes unnecessary with a claims management system in place.
What Is Claims Adjudication?
Claims adjudication is the process of evaluating a submitted insurance claim against applicable coverage, policy conditions, claim data, contractual rules, and payment requirements to determine the appropriate outcome.
The outcome may be approval, denial, partial payment, pending status, or referral for additional review. Claims adjudication is therefore a decisioning activity within the broader claims management lifecycle, rather than a synonym for the entire claims process.
In healthcare, adjudication can involve member eligibility, benefits, provider information, diagnosis and procedure codes, authorization requirements, claim edits, contractual rates, and coordination-of-benefits information. In property and casualty insurance, the evaluation may involve coverage, exclusions, deductibles, liability, supporting documentation, reserves, and settlement authority.
In technical terms, a claims adjudication system evaluates structured claim information against a set of deterministic or configurable conditions and produces a decision or routing outcome.
Claims Processing vs. Claims Adjudication
Claims processing refers to the broader sequence of activities required to receive, validate, evaluate, route, and complete a claim. Claims adjudication is the decisioning component within that process.
For example, a claim processing system may receive the claim, validate required fields, retrieve policy information, collect documents, assign an adjuster, and track workflow state. A claims adjudication system evaluates the relevant claim and policy data to determine whether the claim satisfies the conditions for payment, denial, partial payment, or additional review.
This distinction is important when evaluating claim management software because workflow orchestration and decision logic solve different technical problems.
How Claims Adjudication Works
A claims adjudication system evaluates claim data against a sequence of eligibility, coverage, policy, contractual, and payment rules. The exact logic varies by insurance line, but the technical pattern generally involves the following stages:
- Claim validation: Validate required fields, identifiers, dates, codes, and supporting information.
- Eligibility and coverage validation: Determine whether the claimant, member, asset, or policy was covered for the relevant service or loss.
- Policy and benefit rules: Apply exclusions, deductibles, copayments, limits, authorization requirements, or other applicable conditions.
- Pricing and payment calculation: Determine applicable amounts, insurer responsibility, and claimant responsibility where relevant.
- Exception handling: Route claims that fail automated conditions to manual review, additional documentation, investigation, or approval.
- Final decision: Approve, deny, partially approve, pend, or route the claim based on the applicable rules.
For healthcare organizations, these workflows may also be implemented through medical claims adjudication solutions, healthcare claims adjudication systems, and health insurance claim processing software, depending on the organization's payer, provider, and transaction architecture.
Why Modern Claims Management Depends on Decision Logic, Not Just Workflow Automation?
Automation of the claims process does not necessarily guarantee efficient claims management. Although a workflow describes how a process should be performed, operations dictate what must be done at each step of the process.
Not all claims need to go through the same investigative process. There is no reason why a claim for an unobjectionable motor vehicle, accompanied by full documentation, could not be immediately settled, while a commercial property claim with coverage exceptions would need a different process entirely. The workflow may be similar, but the operational decisions are different.
Many insurers still manage these decisions through application code, spreadsheets, or manually maintained claims guidelines. As products evolve, regulations change, and settlement policies are updated, maintaining these rules across multiple systems becomes increasingly difficult. This is where configurable decision logic becomes essential.
Instead of embedding policies within an application, it has become possible for insurance companies to manage their business rules with respect to handling the claims process centrally.
It is now possible to change coverage validation, adjuster assignment, claims fraud referrals, reserve requirements, authority levels, vendor management, and claims settlement routes according to changes in the business needs without modifying the application.
In this way, a consistent and flexible claims management process can be created. Changes to the operational process can be made fast and assuredly, and every claim is processed in accordance with the latest business rules, regulations, and corporate governance requirements.
Nected's solution facilitates such an approach by using decision orchestration to manage the insurer’s business rules, workflows, AI algorithms, and external data separately from their existing claims applications. Rather than replacing existing claims management platforms, it helps insurers operationalize claim decisions by making policies, approval logic, and routing rules easier to configure as products, regulations, and business requirements evolve.
The same architecture can be applied to claims adjudication. Instead of embedding every adjudication condition inside the claims application, insurers can externalize decision logic for claim routing, approval thresholds, documentation requirements, exception handling, and escalation. The claims application remains responsible for managing the claim record, while the decisioning layer evaluates the conditions that determine the next action.
Also Read: Types of Workflow Automation
Conclusion
Modern claims operations involve far more than processing claims from notification to settlement. Every claim requires coordinated decisions around coverage validation, investigation, reserve management, approvals, vendor collaboration, and regulatory compliance before a settlement can be reached.
As claim volumes grow and operational requirements become more complex, insurers need more than a system to record claim information. They need a structured approach to managing how claims progress, how operational decisions are applied, and how different teams remain aligned throughout the lifecycle.
Claims management system software provides this operational basis. Coupled with adjustable decision logic, it allows insurance companies to standardize the claims processing process while being sufficiently adaptable to adjust to changing business policies, regulations, and claims processing procedures.
Frequently Asked Questions
What is claims management system software?
Claims management system software is used by insurance companies to process claims that range from First Notice of Loss (FNOL) to claim settlement. The software offers claim registration, claim investigation, document management, reserve management, approval, payment and operational monitoring throughout the claims management process.
How does claims management software assist in claims processing?
It creates a systematic platform to coordinate claim processes, document management, assignment of tasks, operational monitoring and visibility throughout the entire process of claims processing.
What is done between FNOL and claim settlement?
Once the claim is filed by the customer, the insurer verifies the policy coverage, reviews the documents, investigates the loss, creates the reserve, coordinates with the adjusters/vendors, approves the claim and settles the same before closing the claim.
Why isn't workflow automation enough for claims management?
Workflows define the sequence of claim activities, but they don't determine how operational decisions should be made. Coverage validations, fraud referrals, reserve approvals, adjusters’ appointments, and settlement routing require configurable business rules that can be altered as per the changes in the product, regulations, and internal policies.
What features must an insurer consider in the software solution for claims management?
An insurer needs to consider the following aspects when considering a claims management solution: End-to-end claims process, centralized claims data, configurable workflows, operational visibility, integration with policies and payments, and adaptive decision logic.